Florida Housing Affordability: Amendment 3 Is Just the Start
THE AMERICAN DREAM IS GETTING FURTHER OUT OF REACH: AMENDMENT 3 IS JUST THE START
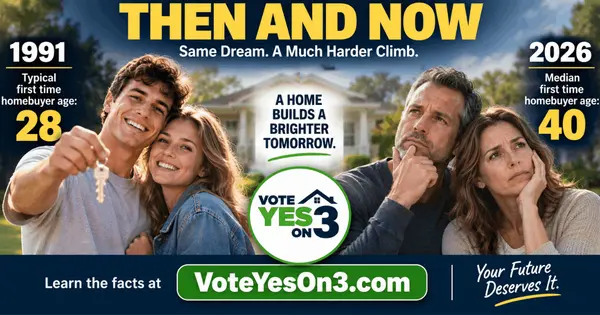
When I started selling real estate in Tampa Bay in 1991, the typical first time home buyer in America was 28 years old. Today, that buyer is 40. Of all the statistics I have seen about today's housing market, that may concern me the most. We have pushed the starting line of homeownership back approximately 12 years in one generation. If we don't start addressing housing affordability from several different directions, where does that number go next? Forty five? Fifty? At some point, homeownership risks becoming something many middle class and working class Americans simply cannot reach. And that affects much more than where somebody lives.
When I started selling real estate in Tampa Bay in 1991, the typical first time home buyer in America was 28 years old. Today, that buyer is 40. Of all the statistics I have seen about today's housing market, that may concern me the most. We have pushed the starting line of homeownership back approximately 12 years in one generation. If we don't start addressing housing affordability from several different directions, where does that number go next? Forty five? Fifty? At some point, homeownership risks becoming something many middle class and working class Americans simply cannot reach. And that affects much more than where somebody lives.
HOMEOWNERSHIP HAS ALWAYS BEEN ABOUT BUILDING WEALTH
For generations, owning a home has been one of the primary ways ordinary American families have accumulated wealth. You buy a home. You make your mortgage payments. You gradually reduce what you owe. Over the long term, the property may appreciate. Eventually, you can reach retirement with substantial equity or perhaps a completely paid off home. That becomes a nest egg. It becomes retirement security. It can become something you pass along to your children. But that process requires something today's buyers are increasingly losing. Time. Consider a simple 30 year mortgage. Someone buying their first home at 28 could theoretically reach the end of that mortgage at 58. Someone starting at 40 reaches 70. If the typical first time buyer eventually becomes 50, that same timeline takes them to 80. Of course, people refinance, move, sell and pay mortgages off early. I'm not suggesting everyone keeps the same mortgage for exactly 30 years. The point is the starting line. We've already moved it back 12 years.
For generations, owning a home has been one of the primary ways ordinary American families have accumulated wealth. You buy a home. You make your mortgage payments. You gradually reduce what you owe. Over the long term, the property may appreciate. Eventually, you can reach retirement with substantial equity or perhaps a completely paid off home. That becomes a nest egg. It becomes retirement security. It can become something you pass along to your children. But that process requires something today's buyers are increasingly losing. Time. Consider a simple 30 year mortgage. Someone buying their first home at 28 could theoretically reach the end of that mortgage at 58. Someone starting at 40 reaches 70. If the typical first time buyer eventually becomes 50, that same timeline takes them to 80. Of course, people refinance, move, sell and pay mortgages off early. I'm not suggesting everyone keeps the same mortgage for exactly 30 years. The point is the starting line. We've already moved it back 12 years.
THE NUMBERS HAVE CHANGED DRAMATICALLY SINCE 1991
When I entered real estate in 1991, the median Florida single family home sold for approximately $80,000. Florida's median household income was approximately $27,250. The median home therefore cost roughly 2.9 times the median household income. Today, a typical Tampa area home is roughly $400,000, depending on the specific measurement and geographic area being used. The latest available statewide median household income is approximately $75,630. Income has gone up considerably. Home prices have gone up much faster. And the purchase price isn't the only problem. Today's Florida buyer also has to contend with homeowners insurance, property taxes, mortgage rates, utilities, maintenance and the overall increase in the cost of living. That's why I don't believe housing affordability can be fixed by attacking one issue. It is a four legged stool.
When I entered real estate in 1991, the median Florida single family home sold for approximately $80,000. Florida's median household income was approximately $27,250. The median home therefore cost roughly 2.9 times the median household income. Today, a typical Tampa area home is roughly $400,000, depending on the specific measurement and geographic area being used. The latest available statewide median household income is approximately $75,630. Income has gone up considerably. Home prices have gone up much faster. And the purchase price isn't the only problem. Today's Florida buyer also has to contend with homeowners insurance, property taxes, mortgage rates, utilities, maintenance and the overall increase in the cost of living. That's why I don't believe housing affordability can be fixed by attacking one issue. It is a four legged stool.
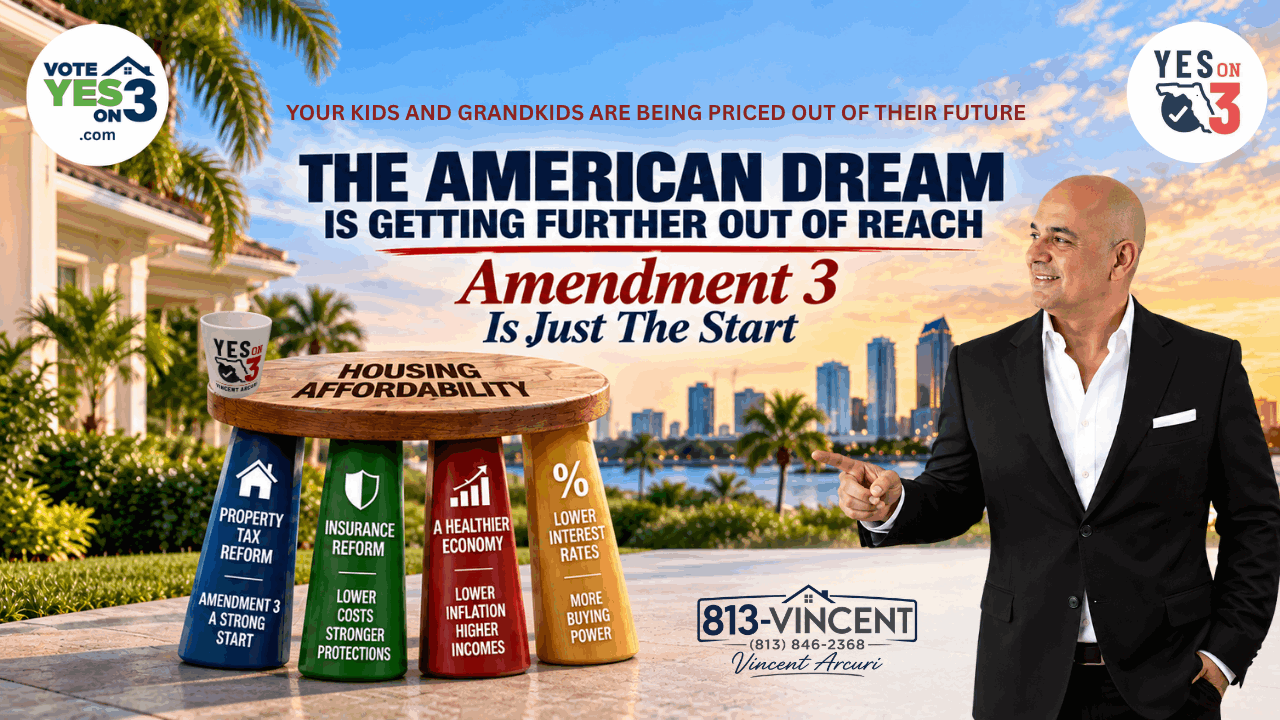
THE FOUR LEGGED STOOL OF HOUSING AFFORDABILITY
If we're serious about making homeownership attainable again, I believe four things have to happen. We need property tax reform. We need continued homeowners insurance reform. We need a healthier economy with inflation under control and household incomes able to keep pace. And we need mortgage rates to become more affordable. Those are the four legs. Fixing one helps. Fixing all four could fundamentally change the affordability equation.
If we're serious about making homeownership attainable again, I believe four things have to happen. We need property tax reform. We need continued homeowners insurance reform. We need a healthier economy with inflation under control and household incomes able to keep pace. And we need mortgage rates to become more affordable. Those are the four legs. Fixing one helps. Fixing all four could fundamentally change the affordability equation.
LEG ONE: PROPERTY TAX REFORM
When I started selling real estate in 1991, Florida's basic homestead exemption was $25,000. Today, qualifying Florida homeowners can receive up to $50,000 in homestead exemption, with the additional portion applying to non school property taxes. Meanwhile, home values have increased dramatically. The exemption simply hasn't kept pace with the cost of housing. That's why I support Amendment 3. If approved by at least 60 percent of Florida voters on November 3, Amendment 3 would increase the homestead exemption for non school property taxes to $150,000 in 2027 and $250,000 in 2028, with inflation adjustments thereafter.
Will that solve housing affordability? Absolutely not. But it's a start.
When I started selling real estate in 1991, Florida's basic homestead exemption was $25,000. Today, qualifying Florida homeowners can receive up to $50,000 in homestead exemption, with the additional portion applying to non school property taxes. Meanwhile, home values have increased dramatically. The exemption simply hasn't kept pace with the cost of housing. That's why I support Amendment 3. If approved by at least 60 percent of Florida voters on November 3, Amendment 3 would increase the homestead exemption for non school property taxes to $150,000 in 2027 and $250,000 in 2028, with inflation adjustments thereafter.
Will that solve housing affordability? Absolutely not. But it's a start.
LEG TWO: HOMEOWNERS INSURANCE REFORM
You cannot have a serious conversation about Florida housing affordability without talking about homeowners insurance. Florida has already enacted significant insurance legislation, and we need to continue working toward a competitive and stable insurance market that provides meaningful protection at a cost homeowners can afford. Here's what matters to the buyer sitting at the kitchen table trying to figure out whether they can afford a house. They don't care which part of their payment is called principal, interest, taxes or insurance. They care about the number at the bottom. What does this house cost me every month? If insurance adds hundreds of dollars to that monthly expense, the buyer's purchasing power goes down. That's an affordability problem.
You cannot have a serious conversation about Florida housing affordability without talking about homeowners insurance. Florida has already enacted significant insurance legislation, and we need to continue working toward a competitive and stable insurance market that provides meaningful protection at a cost homeowners can afford. Here's what matters to the buyer sitting at the kitchen table trying to figure out whether they can afford a house. They don't care which part of their payment is called principal, interest, taxes or insurance. They care about the number at the bottom. What does this house cost me every month? If insurance adds hundreds of dollars to that monthly expense, the buyer's purchasing power goes down. That's an affordability problem.
LEG THREE: THE ECONOMY AND INFLATION
Housing doesn't exist in a vacuum. Families have to buy groceries. They have electric bills. They have car payments. They have health care expenses. They have insurance. They have children. They have everyday living expenses. When inflation drives those costs higher, there is less money available for housing. We need an economy where household income has an opportunity to catch up and where inflation isn't constantly eating away at purchasing power. The stronger the household balance sheet becomes, the more opportunity that family has to become a homeowner.
Housing doesn't exist in a vacuum. Families have to buy groceries. They have electric bills. They have car payments. They have health care expenses. They have insurance. They have children. They have everyday living expenses. When inflation drives those costs higher, there is less money available for housing. We need an economy where household income has an opportunity to catch up and where inflation isn't constantly eating away at purchasing power. The stronger the household balance sheet becomes, the more opportunity that family has to become a homeowner.
LEG FOUR: INTEREST RATES
Then we have mortgage rates. Here's something a lot of people may find surprising. Mortgage rates were actually higher when I started selling real estate. Thirty year mortgage rates averaged roughly 9 percent in 1991. As of September 10, 2026, Freddie Mac reported an average 30 year fixed mortgage rate of 6.76 percent. So today's affordability problem cannot simply be blamed on interest rates. But rates still matter tremendously. A lower mortgage rate can reduce the monthly payment on the same house or allow a buyer to afford more home with the same payment. If inflation continues to improve and economic conditions allow mortgage rates to move lower, that becomes another important piece of the affordability puzzle.
Then we have mortgage rates. Here's something a lot of people may find surprising. Mortgage rates were actually higher when I started selling real estate. Thirty year mortgage rates averaged roughly 9 percent in 1991. As of September 10, 2026, Freddie Mac reported an average 30 year fixed mortgage rate of 6.76 percent. So today's affordability problem cannot simply be blamed on interest rates. But rates still matter tremendously. A lower mortgage rate can reduce the monthly payment on the same house or allow a buyer to afford more home with the same payment. If inflation continues to improve and economic conditions allow mortgage rates to move lower, that becomes another important piece of the affordability puzzle.
PUT THE FOUR LEGS TOGETHER
Now imagine what happens if all four begin moving in the right direction. Property tax relief reduces one component of homeownership costs. Insurance reform reduces another. Lower inflation allows household purchasing power to recover. Lower mortgage rates reduce financing costs. Suddenly, the monthly cost of owning a home begins looking different. And that's when the real estate market has a better opportunity to do what it has always done.
Now imagine what happens if all four begin moving in the right direction. Property tax relief reduces one component of homeownership costs. Insurance reform reduces another. Lower inflation allows household purchasing power to recover. Lower mortgage rates reduce financing costs. Suddenly, the monthly cost of owning a home begins looking different. And that's when the real estate market has a better opportunity to do what it has always done.
REAL ESTATE MARKETS HAVE ALWAYS CORRECTED
I've been selling real estate since 1991. I've seen booming markets. I've seen terrible markets. I've seen recessions. I've seen housing crashes. I've seen bidding wars. I've seen high interest rates and incredibly low interest rates.
One thing I've learned is that real estate markets have a remarkable ability to correct themselves. If home prices get too high and buyers stop buying, inventory rises. Sellers become more competitive. Prices stabilize. Some prices come down. Eventually buyers begin seeing value again. That's supply and demand. But today's affordability problem has outside forces affecting that natural correction.
I've been selling real estate since 1991. I've seen booming markets. I've seen terrible markets. I've seen recessions. I've seen housing crashes. I've seen bidding wars. I've seen high interest rates and incredibly low interest rates.
One thing I've learned is that real estate markets have a remarkable ability to correct themselves. If home prices get too high and buyers stop buying, inventory rises. Sellers become more competitive. Prices stabilize. Some prices come down. Eventually buyers begin seeing value again. That's supply and demand. But today's affordability problem has outside forces affecting that natural correction.
A seller can lower the price of a house.
A seller cannot lower the buyer's homeowners insurance premium.
A seller cannot change Florida's property tax system.
A seller cannot lower mortgage rates.
A seller cannot stop inflation.
A seller cannot lower the buyer's homeowners insurance premium.
A seller cannot change Florida's property tax system.
A seller cannot lower mortgage rates.
A seller cannot stop inflation.
That's why price alone cannot solve today's affordability problem. The market can correct the price of the house. It cannot independently correct every expense surrounding the house.
THE NUMBER 40 SHOULD BE A WARNING
This brings me right back to where I started. The typical first time buyer was 28 when I entered this business. Today they're 40. First time buyers now represent only about 21 percent of home buyers, the lowest percentage recorded by the National Association of Realtors. Those numbers should concern everyone. Because if the next generation can't buy homes, we're not simply creating a housing problem. We're creating a future wealth problem.
Those families lose years of mortgage principal reduction. They lose years of potential appreciation. They lose years of equity accumulation. And they potentially reach retirement without one of the largest assets previous generations of middle class Americans were able to build.
This brings me right back to where I started. The typical first time buyer was 28 when I entered this business. Today they're 40. First time buyers now represent only about 21 percent of home buyers, the lowest percentage recorded by the National Association of Realtors. Those numbers should concern everyone. Because if the next generation can't buy homes, we're not simply creating a housing problem. We're creating a future wealth problem.
Those families lose years of mortgage principal reduction. They lose years of potential appreciation. They lose years of equity accumulation. And they potentially reach retirement without one of the largest assets previous generations of middle class Americans were able to build.
AMENDMENT 3 IS JUST THE START
I don't want anyone reading this to think I'm suggesting Amendment 3 magically fixes Florida housing. It doesn't. Amendment 3 is one leg of the stool. Insurance reform is another. A stronger economy with inflation under control is another. More affordable mortgage rates are another. On November 3, Florida voters cannot vote on mortgage rates. They cannot directly vote on their homeowners insurance premium. They cannot vote inflation away. But they can vote on property tax reform. That's why I believe Amendment 3 matters. It's not the finish line. It's a start. And after watching the typical first time buyer go from age 28 to age 40 during my career, I think it's long past time that we start moving the affordability equation back in the other direction. The American Dream shouldn't belong only to people who are wealthy, people who receive a large inheritance, or people whose parents can help them buy their first house. A teacher should have a chance. A police officer should have a chance. A firefighter should have a chance. A nurse should have a chance. A young couple starting a family should have a chance. Working people should have a chance. Because homeownership isn't just about owning four walls and a roof. It's about stability. It's about building equity. It's about creating wealth. It's about retirement. And it's about giving the next generation an opportunity to own a piece of the American Dream. Amendment 3 is just the start.
Now let's get the other three legs of the stool moving in the right direction too.
Vincent Arcuri
Tampa Bay Realtor Since 1991
Over 35 Years of Real Estate Experience
Tampa Bay Realtor Since 1991
Over 35 Years of Real Estate Experience
Categories
Recent Posts
One of the Biggest Mistakes Home Sellers Make Before Listing Their Home
Florida Property Taxes When Buying a Home: Don’t Let the Seller’s Old Tax Bill Fool You
Amendment 3 Has Me Asking County Government One Simple Question: Where’s My Commission?
WHAT HAPPENS WHEN THE FIRST TIME HOMEBUYER TURNS 60?
Greedy Realtors? Let’s Call Bullshit Bullshit.
Using a Realtor Is Optional. Property Taxes Aren’t.
The Real Doomsday Scenario: What Happens If Amendment 3 Does NOT Pass?
The REAL and RE/MAX Merger is Big, But the Agent Still Matters Most
The Word Nobody in Real Estate Wants to Say Out Loud.... Commission